
Caravan Finance
Freedom, funded. Intelligent loan structures for your luxury caravan or camper.
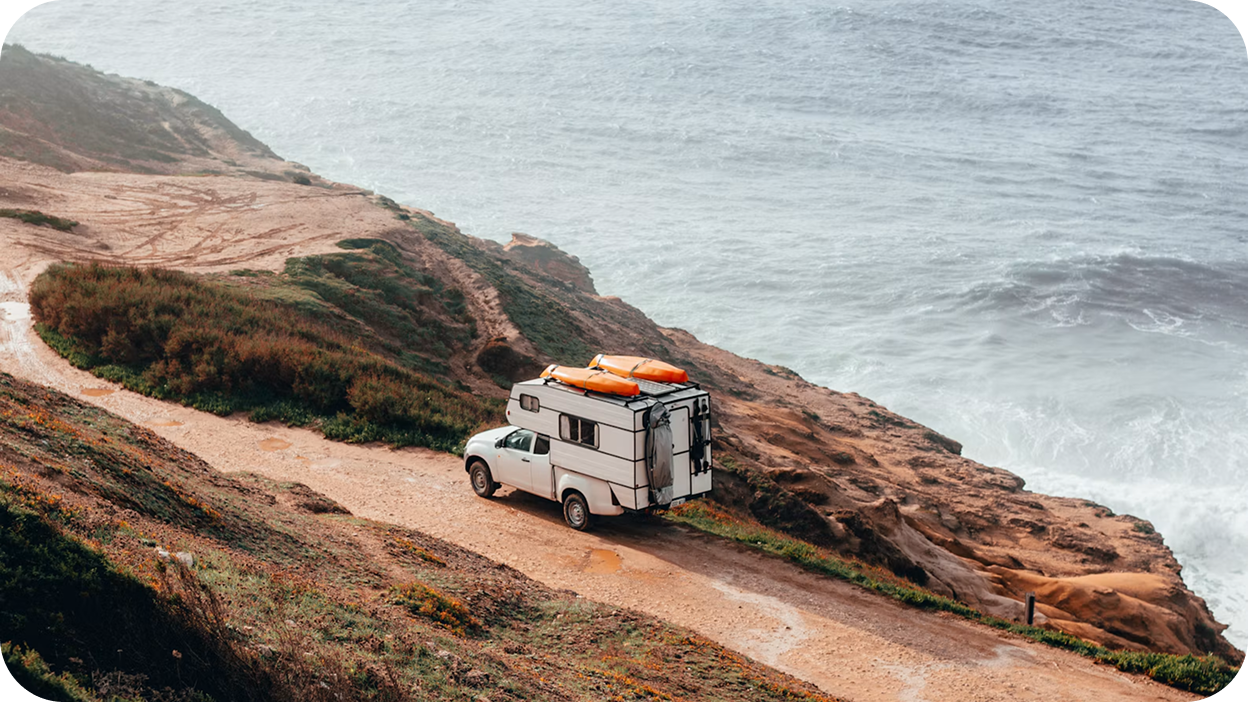
Your next adventure shouldn't be stalled by rigid consumer lending processes. We look past the standard retail banking grids to engineer competitive lifestyle asset finance that preserves your lifestyle cash flow.
Trusted by 100s of SMBs, homeowners, and investors in Australia
We couldn’t recommend Estelle high enough. In what is usually a really stressful time she made us feel valued and heard. She made sure we got a better than best deal with a great bank. Estelle kept us in the loop the entire process and answered any questions we had in a timely manner. We will trust Estelle with all our future endeavours. Thank you for supporting us to achieve our dream.
Jeremy Winter
How Caravan Finance is Actually Evaluated
Walking into a lifestyle dealership usually means being handed a generic finance package backed by a narrow point-of-sale lender.
Lenders evaluate asset finance completely differently based on the age of the vehicle and your chosen security structure. As specialised leisure asset brokers, we cut through the automated dealership algorithms to pitch your application directly to lenders who offer flexible terms for lifestyle assets.
The core policy boundaries that dictate your approval:
The Security Metric
Determining whether your asset qualifies for low-interest secured rates or requires an unsecured structure.
Asset Age Allowances
Sifting through specific lender appetites for vintage models versus brand-new builds.
Policy Over Premium
Selecting a specialist leisure lender that understands consumer cash flow rather than checking standard retail boxes.
Structuring Your Loan:
New vs. Used & Secured vs. Unsecured Options
A common misconception is that all caravan loans are treated identically by banks. In reality, the physical condition and age of the asset dictate the entire underlying framework of your contract.
The structural options we help you navigate:
Secured Caravan Loans
The most popular choice for brand-new or late-model caravans. The caravan itself serves as the underlying collateral, which unlocks the lowest available market interest rates.
Unsecured Caravan Loans
Tailored for older, vintage, or highly customised used caravans that fall outside a bank's standard asset age limits. Because no collateral is tied to the loan, you enjoy complete freedom over how you buy, though it comes with a slightly higher interest margin.
Used Market Freedom
Bypassing dealership restrictions to safely finance caravans purchased through private sellers on platforms like Facebook Marketplace or Caravans For Sale.
Eligible Caravan & Camper Categories
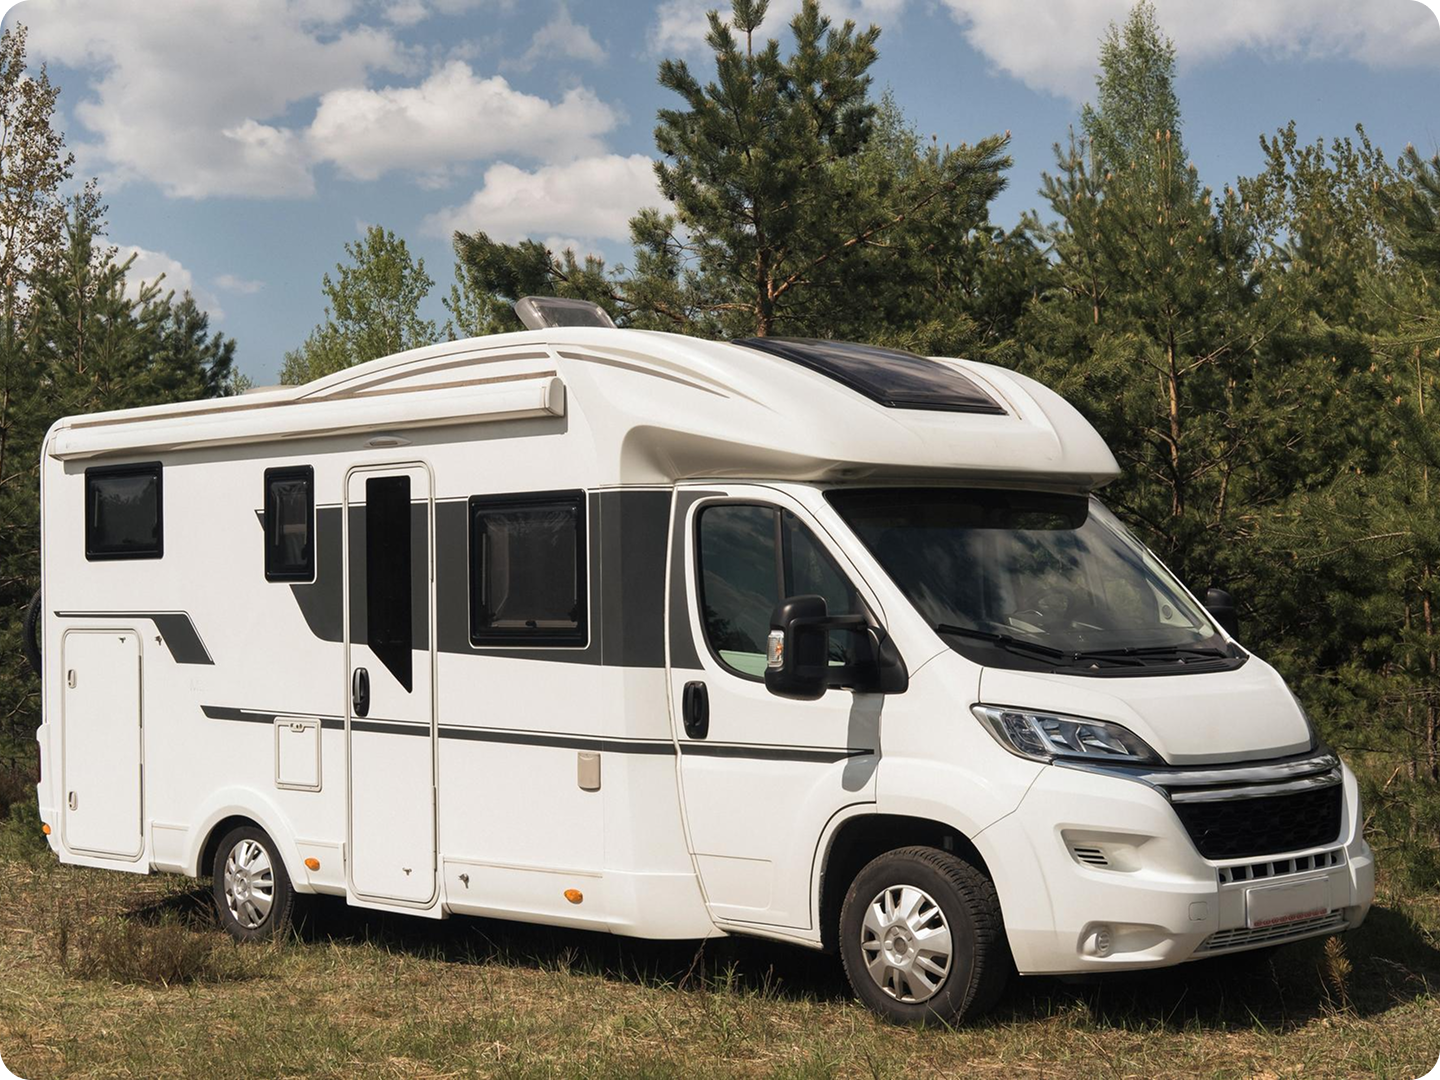
Whether you are looking to purchase a premium caravan for long-haul touring, a rugged off-road camper for weekend getaways, or a fleet of vehicles for commercial hire use, our lender panel offers extensive financing coverage.
-
Touring caravans, off-road campers, pop-top caravans, slide-on campers, and premium motorhomes.
-
Campervans, light hybrid camper trailers, and custom lifestyle transport setups.
-
Mobile accommodation units, site cabins, and equipment purchased specifically for commercial rental or hire fleets (lender dependent).
Tailored Capital Configurations:
Deposits, Terms, and Balloon Options
You should never commit to a payment plan that puts immediate strain on your weekly household budget. We configure your loan components to keep your outgoings perfectly sustainable.
How we optimise your lifestyle asset file:
Zero Deposit Pathways
Sourcing competitive policies that allow you to borrow 100% of the purchase price plus initial registration costs, keeping your personal cash cushions intact.
Flexible Amortisation Terms
Spreading the capital cost over terms ranging from 1 to 7 years to precisely hit your target monthly repayment figures.
Residual Balloon Injections
Lowering your regular repayments by deferring a lump-sum percentage of the loan balance to the absolute end of the finance term.
The Commercial Play:
Financing a Caravan Through Your Business
For self-employed business owners, company directors, and contractors, it is entirely possible to acquire lifestyle assets under a commercial framework if the vehicle serves a legitimate operational purpose.
The streamlined commercial pathways we build for growing entities:
The Business Purpose Test
If you use your caravan for site accommodation, mobile consulting, commercial photography, or regional project management, we can package it under a business framework.
Tax and Depreciation Leverage
Aligning the purchase with your active ABN to potentially tap into business interest deductions and asset write-off advantages.
Streamlined Low-Doc Processing
Bypassing complex personal financial testing by verifying your borrowing profile through simple business bank statement analysis.
Caravan Finance FAQs
-
Caravan loans are typically structured over flexible terms ranging from 1 to 7 years. Choosing a longer term helps minimise your ongoing monthly repayments, while a shorter term allows you to clear the debt faster and reduce the total interest paid over the life of the loan.
-
Yes. You can comfortably finance used caravans, whether they are purchased directly from a registered commercial dealership or via a private individual. For older or highly customised vintage caravans, we simply pivot your file toward specialised lenders on our panel that do not enforce strict asset-age caps.
-
In many cases, you do not need a deposit at all. Our extensive leisure panel features multiple lenders offering 100% finance options for both new and qualified used caravans. However, chipping in a cash deposit can help reduce your total loan amount and secure a lower interest tier.
-
Yes. If you are self-employed and the caravan is utilised for a verified business purpose—such as mobile on-site operations or regional work travel—we can structure a commercial asset facility like a Chattel Mortgage to optimise your tax position.
-
Yes. You do not need standard corporate payslips to get a caravan loan. We specialise in sole trader and director asset structuring, utilising alternative documentation like your active ABN and business bank statements to secure clean, fast approvals.